1
Usually 0% VAT
Cold takeaway food
If it is taken away and eaten off the premises.
Providing UK hospitality and retail businesses with powerful, easy-to-use EPOS technology. From seamless order management to real-time reporting — we’re your trusted partner for long-term success.
View Our PackagesIntuitivePOS
A simple storyboard guide for restaurants
If it is taken away and eaten off the premises.
If it is eaten in your restaurant or seating area.
Hot food and hot drinks are standard-rated.
Examples: soft drinks, bottled water, crisps, confectionery and ice cream.
Use separate takeaway and eat-in buttons in your EPOS.
Keep clear reports when you have both dine-in and takeaway sales.
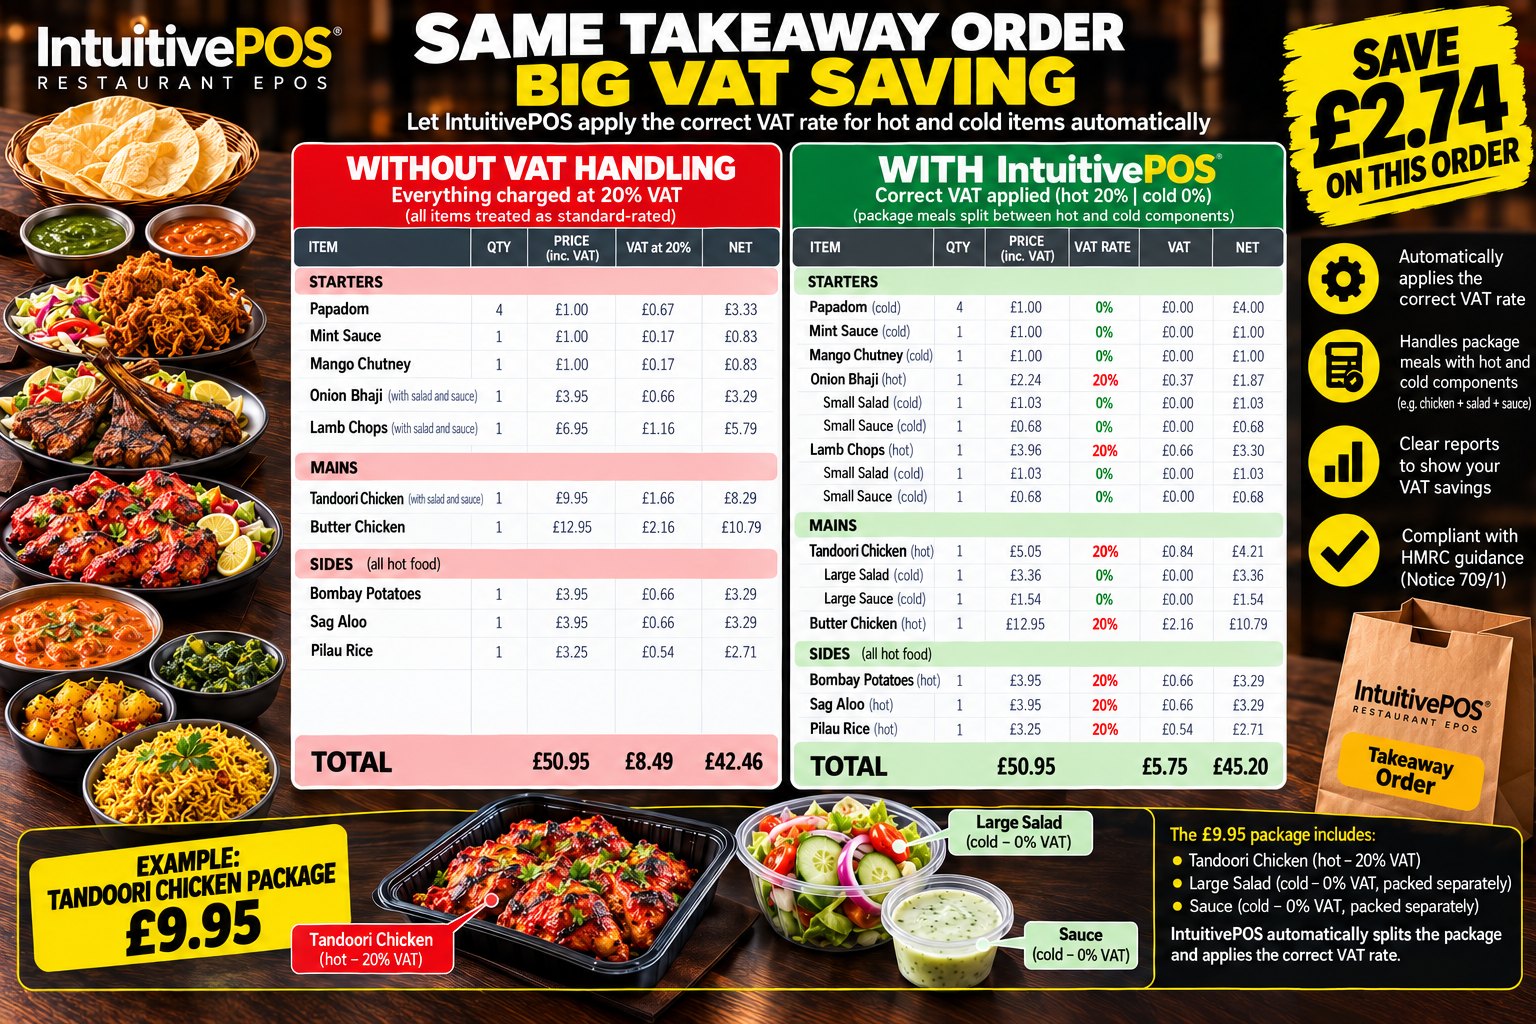
General guidance only. Check HMRC guidance for your exact VAT treatment.
For example, a £10 Tandoori Chicken Meal includes hot tandoori chicken, cold salad and cold sauce. If the items are genuinely separate components and can also be bought separately, HMRC normally treats this as a mixed supply. The £10 selling price should be fairly divided between the different components.
https://www.gov.uk/guidance/catering-takeaway-food-and-vat-notice-7091
No. Many qualifying cold takeaway foods can be zero-rated, but some products such as confectionery, crisps, ice cream, bottled water and certain drinks remain standard-rated.
Food and drink supplied for consumption on the premises is generally standard-rated, even where the same cold food could qualify for zero-rating when taken away.
Hot takeaway food is generally standard-rated at 20% where HMRC’s hot-food conditions are met.
Potentially, yes. A qualifying cold sandwich sold to be taken away and eaten off the premises can normally be zero-rated.
You need to distinguish between the two. HMRC says businesses with both types of sale need to correctly identify or fairly apportion qualifying cold-food sales between eat-in and takeaway.
IntuitivePOS can be configured so staff select Eat In or Takeaway, allowing the EPOS to apply the VAT rules you have configured to the relevant products and keep clearer sales records.
If qualifying takeaway sales are currently being incorrectly treated as standard-rated, applying the correct VAT treatment could reduce VAT overpayments. The actual saving depends on your products and sales mix.
Yes. HMRC requires satisfactory evidence where businesses need to distinguish or apportion qualifying cold takeaway sales from on-premises sales.
No. The restaurant remains responsible for applying the correct VAT treatment. IntuitivePOS can help automate the rules once they have been correctly configured.